


Remitly Global Doesn't Pay a Dividend and Constantly Dilutes Shareholders. Here's Why I'd Still Buy and Hold It Forever.
Remitly Global Doesn't Pay a Dividend and Constantly Dilutes Shareholders. Here's Why I'd Still Buy and Hold It Forever.
Brett Schafer, The Motley FoolSat, September 26, 2026 at 6:25 AM UTC
0

Image source: Getty Images.Key Points -
Remitly is growing its revenue per share.
Profit margins are expanding quickly.
The stock looks very cheap at today's prices.
10 stocks we like better than Remitly Global ›
Value-focused investors might ignore stocks with a high trailing price-to-earnings ratio (P/E), no dividend payments, and consistent shareholder dilution. That describes Remitly Global(NASDAQ: RELY) perfectly. And yet, I think it is a great value for investors looking to buy right now.
The remittance disruptor is consistently gaining market share and expanding globally with its mobile-first service, driving consistent revenue and earnings growth. Here's why -- despite shareholder dilution -- I would buy Remitly stock today and hold it forever.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Growth on a per-share basis
Remittances are international money transfers, and used to have high fees charged by providers like Western Union and global banks. Remitly is a modern solution that drives down costs for consumers and businesses while allowing them to send money digitally to various destinations around the world, including digital bank accounts or cash pick-up.
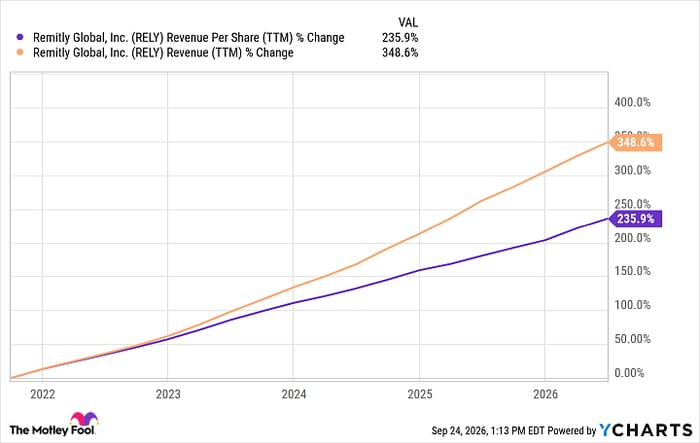
This isn't just talk; Remitly has delivered financial results for years. Last quarter, active customers grew 20% to 10.2 million, up from just 2.4 million back in 2022. Revenue grew to $495 million in the quarter and is up 350% in the last five years. Even if you use revenue per share to account for share count growth, revenue is up 236% over five years, indicating phenomenal market-share gains.
Long-term, there is still a massive opportunity for Remitly to gain users, with hundreds of millions of customers who send money across borders and tens of trillions in annual payment volume. It processed just $23.5 billion in volume last quarter. As the leading disruptor in the space, Remitly should steal a lot of this share over the long term.
Profitability inflection
Based on Remitly's trailing earnings, the stock may seem expensive. Trailing EBIT (earnings before interest and taxes) was $187 million, which is a multiple of 24x. Not overly expensive compared to a lot of stocks, but not a screaming-cheap value pick.
This actually understates Remitly's forward earnings power because of the significant margin expansion it is undergoing. Operating margin was 13.5% last quarter and has been rising at a steady clip. If Remitly grows its trailing revenue to $2 billion over the next few quarters and maintains an operating margin of 15%, that would imply $300 million in earnings, or close to 10x its current market cap.
That makes the stock much cheaper than it appears at first glance.
RELY Revenue Per Share (TTM) data by YCharts
Advertisement
Should you buy Remitly stock?
Investors have soured on Remitly in recent weeks for two reasons. First, Latin American bank Nu Holdings launched a U.S. bank account that can send remittances. While potentially a competitive threat to Remitly, many banks offer remittances to customers, and they cannot do so at the same prices with sustainable economics without the same direct financial connections worldwide. I doubt this is a threat.
Another narrative is building around AI agents such as Meta Platforms' Muse. These agents can theoretically search for competing remittance products for users, shifting volumes to the cheapest possible and driving down costs. However, in most cases, Remitly is one of the cheapest options for sending volume remittances, meaning agents could be a tailwind for the business if they achieve mass adoption.
This is allowing investors to buy Remitly shares at a discount once again. The company is growing quickly, not diluting shareholders too much, and seeing a nice earnings inflection. Long-term, it is also adding new services for members such as savings accounts and international spending cards, which could further drive revenue growth.
If Remitly can grow its revenue to $3 billion and maintain 20% profit margins, that would represent $600 million in annual earnings power. Compared to its market cap of $4.37 billion, that is an earnings multiple of just 7, making Remitly a great stock to buy and never sell.
Should you buy stock in Remitly Global right now?
Before you buy stock in Remitly Global, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Remitly Global wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $386,781!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,379,943!*
Now, it’s worth noting Stock Advisor’s total average return is 936% — a market-crushing outperformance compared to 213% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 26, 2026.
Brett Schafer has positions in Nu Holdings and Remitly Global. The Motley Fool has positions in and recommends Meta Platforms and Nu Holdings. The Motley Fool has a disclosure policy.
Source: “AOL Money”
